Finmart review Malaysia November 2026
This review of Finmart combines the facts published on finmart.my with an explanation of its flat-rate example and a comparison with licensed moneylenders. It looks at what the platform actually shows borrowers and where its claims need a closer look.
The main takeaway: Finmart is a free loan comparison platform, not a lender. Its search covers RM1,000 to RM20,000 over 12 to 84 months, and it lists banks alongside licensed moneylenders. Its example shows how an “18% flat” rate turns into an APR of 30.59%, a gap every Malaysian borrower should understand.
About Finmart
Finmart is a website where you enter an amount and term, see offers from several providers and apply online. It describes itself as a comparison platform that does not issue loans, sign credit agreements or assess creditworthiness. Each lender sets its own approval, rates and fees.
The platform belongs to SIA JEFF, a company registered in Jelgava, Latvia (registration number 43603085405). Its terms are governed by Malaysian law, the service is free for users and users must be 18 or older.
Finmart’s company list mixes two very different groups: banks such as Maybank, CIMB, RHB, Hong Leong Bank and AFFIN Bank, and licensed moneylenders such as Tambadana, Nimbura, AmanahKredit and SakuWang. Banks are licensed by Bank Negara Malaysia, while moneylenders hold licences from KPKT under the Moneylenders Act 1951.
Finmart comparison with other lenders
Both Finmart and Crezu are free matching services, so the table also includes two licensed moneylenders that Finmart lists, to show what borrowing directly looks like.
| Feature | Finmart | Crezu | AmanahKredit | SakuWang |
|---|---|---|---|---|
| Type | Comparison platform, not a lender | Matching service, not a lender | Licensed moneylender | Licensed moneylender |
| Operator | SIA JEFF (Latvia) | Fininity OÜ (Estonia) | Constance Infinity Sdn Bhd | Not named |
| Loan amount | RM1,000–RM20,000 (search range) | RM500–RM10,000 | RM100–RM5,000 | RM500–RM10,000 |
| Term | 12–84 months | 91–120 days | 2–30 days | 1–30 days (as listed on Finmart) |
| Maximum rate | APR 31.72% (18% p.a. flat) | APR 18% | APR 18% | APR 18% |
| Published example | RM10,000 over 36 months: RM15,400 total | RM5,000 over 91 days: RM5,225 total | Not published | Not published |
| Cost of the service | Free | Free | - | - |
| Minimum age | 18 (lenders set their own) | 18 (lenders set their own) | 21 | 21–70 |
Finmart covers the widest range. Its search goes up to RM20,000 and 84 months, against RM10,000 and 120 days at Crezu, and it includes bank personal loans that Crezu and the moneylenders cannot offer. CIMB, for example, is listed with loans up to RM100,000 over five years from 4.38% a year.
Crezu and the moneylenders are clearer about short-term cost. Crezu publishes a RM5,000 example over 91 days, and AmanahKredit and SakuWang state an 18% maximum APR. Finmart shows no rates for individual lenders, only its own platform-wide example.
Finmart loan rate per year
Finmart’s representative example is worth reading closely, because it shows the difference between a flat rate and an APR:
- Loan amount: RM10,000 over 36 months
- Flat rate: 18% a year
- Total interest: RM10,000 × 18% × 3 years = RM5,400
- Total repayable: RM10,000 + RM5,400 = RM15,400
- Monthly instalment: RM15,400 ÷ 36 = RM427.78
- Equivalent APR: 30.59%, before any fees
A flat rate charges interest on the full amount for the whole term, even though you repay part of the loan every month. That is why 18% flat equals about 30.6% APR here. When comparing offers on Finmart, use the APR, not the flat rate.
Finmart states a maximum APR of 31.72%, and any fees come on top. For comparison, a three-year RM10,000 bank loan at CIMB’s advertised starting rate of 4.38% a year would cost far less, so salaried borrowers with a good record should check bank offers first.
Finmart pros and cons
Pros
- Banks and moneylenders in one place: from short-term microloans to bank personal loans.
- Free to use: no fees for comparing or applying.
- Named lenders: each provider is shown by name, with amount ranges and age limits.
- An honest example that converts the flat rate into an APR.
- Available in English and Bahasa Melayu, with support by email six days a week.
Cons
- No rates per lender: interest and fees appear only in each lender’s own offer.
- Sponsored listings: the ranking is partly paid placement.
- The 12–84 month search does not match the 1–30 day terms of many listed moneylenders.
- No phone support, and the operator is based in Latvia.
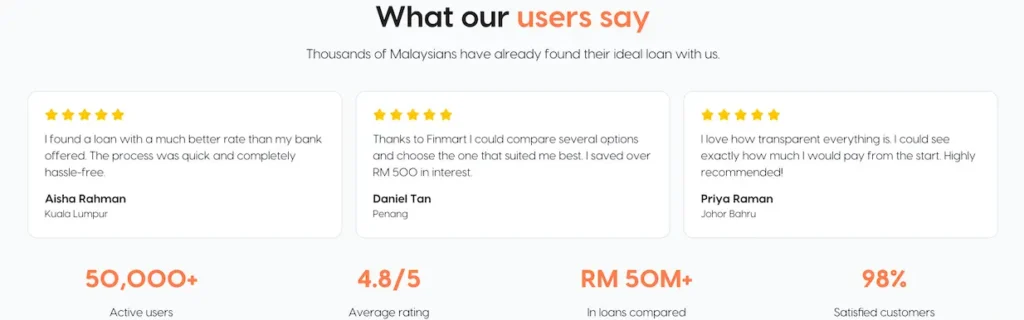
- Its 4.8/5 rating and user numbers are self-reported.
How do you apply and compare loans on Finmart?
Finmart says a comparison takes about three minutes and needs no physical documents.
- Set the amount (RM1,000 to RM20,000) and the term in the calculator.
- Browse the listed offers or fill in the preliminary questionnaire, which Finmart forwards to partners to check your eligibility.
- Choose an offer and compare its APR, term and total repayment with the alternatives.
- Apply directly with the chosen bank or moneylender, which decides on approval and signs the agreement with you.
Requirements
- Age 18 or older to use Finmart
- The lender’s own age range, which varies from 18–70 to 21–60 in Finmart’s listings
- Your MyKad, proof of income and bank details, as each lender requires
-
Info and review SakuWang Ambil pinjaman untuk keperluan kecemasan dengan tempoh 3-6 bulan dan APR maksimum 18%, dana terus ke akaun bank anda (semak kontrak untuk kos sebenar).Apply now
-
Info and review Nimbura Seorang pelanggan memohon pinjaman sebanyak RM2000 untuk 3 bulan (90 hari). Faedah dikira sebagai RM2000 × 90 × 0.05% = RM90. Jumlah bayaran balik ialah RM2000 + RM90 = RM2090. Bayaran bulanan ialah RM2090 / 3 = RM696.67.Apply now
-
Info and review Tambadana Cik Siti memohon pinjaman sebanyak RM5,000 untuk 3 bulan (90 hari). Jumlah bayaran lebihan mengenai faedah pinjaman Cik Siti ialah RM5,000 x 90 x 0.05% = RM225. Bayaran penuh Cik Siti ialah RM5,000+RM227.50 = RM5,225. Bayaran bulanan yang perlu dibayar oleh Siti ialah RM5,225/3 = RM1,741.67.Apply now


What if you cannot repay a loan found on Finmart?
Finmart sets no rules of its own beyond the age limit, so repayment problems are handled between you and the lender.
- Finmart plays no part in repayment; the lender’s agreement sets the late charges.
- Licensed moneylenders may charge at most 18% a year on unsecured loans and may add no charges beyond stamp duty and attestation fees.
- Talk to the lender before the due date to agree a new schedule.
- Report harassment by a moneylender to KPKT.
- AKPK, the credit counselling agency set up by Bank Negara Malaysia, offers free debt advice.
Finmart contact details
Finmart offers support by email, Monday to Saturday. Its 50,000+ users and 4.8/5 rating are figures from its own homepage and have not been independently verified.
- Company: SIA JEFF (registration number 43603085405)
- Address: Viktorijas iela 25, Jelgava, LV-3001, Latvia
- Email: info@finmart.my
- Malaysia
Frequently asked questions about Finmart
-
Is Finmart a licensed lender in Malaysia?
-
Who owns Finmart?
-
Is Finmart free to use?
-
How much can I borrow through Finmart?
-
What does a loan found on Finmart cost?
-
What is the difference between a flat rate and APR?
-
Are the offers on Finmart ranked fairly?
-
Does Finmart check my credit?
-
How do I repay a loan found on Finmart?
-
How do I contact Finmart?
