Kredio review South Africa October 2026
This is a combined review of Kredio: key facts from its website and legal documents, plus a side-by-side comparison with other short-term lenders in South Africa.
Kredio offers R500–R8,000 over 7–45 days to borrowers aged 21 and over, and says funds usually reach the bank account within 15 minutes of approval. It presents itself as a registered credit provider, not a matching service. It publishes no interest rate or fee figures, and no HelloPeter or Trustpilot review history was found, so cost and reputation remain open questions.
About Kredio
Kredio does not publish an interest rate, initiation fee or monthly service fee on its website, so the total cost appears only after an application. Its terms promise a pre-agreement statement and quotation before the credit agreement is signed, and the homepage says the full cost is shown before applying.
Under the National Credit Act (NCA), short-term credit means loans up to R8,000 repayable within 6 months, with interest stated per month and initiation and service fees charged separately. Kredio’s R8,000 ceiling and 61-day maximum term fit within the amount and term limits of that definition. A worked example is not possible without Kredio’s figures, so compare the total repayable on the quote with the amount borrowed.
Kredio says early repayment carries no penalty and can reduce total interest. Its terms credit each payment first to interest, then to fees and charges, and last to the principal.
Kredio pros and cons
The facts above produce a mixed picture: strong limits and speed on paper, thin disclosure on cost and track record.
Pros
- Highest ceiling in the comparison: R8,000 covers larger short-term needs than CreditBar’s R5,000 limit.
- Fast payout claimed: in most cases within 15 minutes of approval, according to Kredio.
- Short document list: a valid South African ID, three months of bank statements and an active phone number.
- Flexible repayment: DebiCheck debit order, manual EFT, Capitec Pay, Ozow or card.
- Early repayment without penalty, per Kredio, with a settlement letter available from the customer profile.
Cons
- No published interest rate, initiation fee, service fee or representative example, so cost cannot be compared in advance.
- Minimum age of 21, against 18 at CreditBar.
- Recently incorporated company with no HelloPeter or Trustpilot history found.
- Inconsistent site details: the term appears as 7–61 days in the FAQ and 7–45 days in the advantages list, and payout as 15 minutes on one page and within an hour on another.
- No phone number or working hours published, only live chat, email and a postal address.
How does Kredio compare with other short-term lenders?
Kredio has the highest loan ceiling in the comparison below, at R8,000 against R5,000 at CreditBar and R4,000 for a first loan at PrimeLoans. It also lists more repayment channels than the other two on the pages reviewed. All figures come from each lender’s own website.
| Feature | Kredio | CreditBar | PrimeLoans |
|---|---|---|---|
| Loan amount | R500–R8,000 | R500–R5,000 | Up to R4,000 (first loan) |
| Term | 7–45 days | 7–45 days | Not stated |
| Minimum age | 21 | 18 | Not stated |
| Payout speed | 15 minutes | 15 minutes | 15 minutes |
| Documents | SA ID, 3 months' bank statements, phone number | SA ID, 3 months' bank statements, bank account | ID, 3 bank statements, payslip, proof of residence |
| Repayment | DebiCheck debit order, EFT, Capitec Pay, Ozow, card | Debit order, manual EFT | DebiCheck debit order, Ozow (early repayment) |
| Customer phone line | Not published | +27 21 301 0526 | +27 21 139 0909 |
Competitors win on a few points. CreditBar accepts borrowers from 18, while Kredio starts at 21. CreditBar and PrimeLoans publish a support phone number, and Kredio lists live chat and email only. None of the pages reviewed for these lenders publishes a rate or fee figure, so cost cannot be compared until each lender issues a quote.
Kredio in official register
The comparison assumes Kredio is the lender and not a broker, so registration status comes first. Kredio presents itself as a registered credit provider, and its terms and conditions list the business description as credit provider. They state that Kredio (Pty) Ltd is registered with the National Credit Regulator (NCR) under number NCRP24149.
That number could not be checked against the NCR register at the time of writing. It is also written NCRP, while credit provider numbers normally take the form NCRCP followed by digits, so confirm the entry on the NCR register before applying. The company registration number indicates that Kredio (Pty) Ltd was incorporated recently, which means there is no long operating record to review.
How do you apply for a Kredio loan?
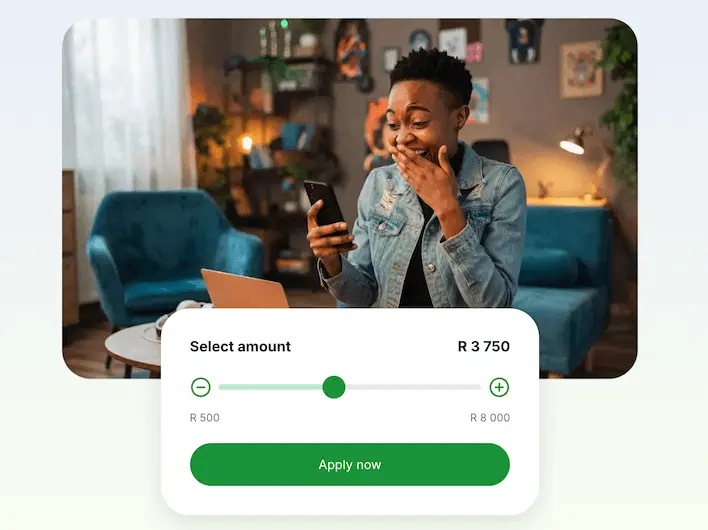
Applying takes five steps, all online.
- Create an account with your phone number and verify it by SMS.
- Enter your personal, employment and income details.
- Add your bank details and provide three months of bank statements. Kredio says statements are uploaded automatically in most cases and manually in some.
- Wait for the automated review, which Kredio says takes minutes during business hours.
- Review and sign the loan agreement online, confirm the DebiCheck debit order through your bank, and receive the funds in your bank account.
Kredio says money usually arrives within 15 minutes of approval, although its application page also says within an hour. Plan for the longer time if the funds are urgent.
Requirements for Kredio
Kredio suits a borrower aged 21 or over who needs more than R5,000 for a short period, can show three months of bank statements with steady income, and is comfortable confirming a DebiCheck debit order. It also fits anyone who wants to apply and sign entirely online.
Four groups should look elsewhere. Anyone under 21 is ruled out by the minimum age. Anyone who wants to see rates and fees before applying will not find them on Kredio’s site. Anyone under debt review generally cannot take new credit under the NCA, and Kredio does not state its own policy. Anyone who wants to phone a lender can compare Jabulanimoney, which publishes a support number.
Missed payment in Kredio
- Kredio asks borrowers to contact it as soon as possible by live chat or email, and says its specialists review the situation and offer repayment options.
- Late-payment fees and penalty interest are not published.
- Repayments are collected by DebiCheck debit order on the due date or made by EFT, and Kredio may send SMS or email reminders beforehand.
- Payments are allocated to interest first, then fees and charges, then the principal.
- Borrowers keep their NCA rights to alternative dispute resolution, an NCR complaint or a National Credit Tribunal application.
How can you contact Kredio?
Kredio (Pty) Ltd publishes three contact channels:
- Live chat
- Email: contact@kredio.co.za
- Address: 82 Tulip Gardens, 17 Langeveld Road, Vorna Valley, Midrand, Gauteng, 1686
- Phone and working hours: not published
Frequently asked questions about Kredio
-
Is Kredio registered with the NCR?
-
Is Kredio a lender or a matching service?
-
How much can I borrow from Kredio and for how long?
-
What does a Kredio loan cost?
-
Can I apply for a Kredio loan with bad credit or while under debt review?
-
What documents do I need to apply to Kredio?
-
How fast does Kredio pay out?
-
How do I repay a Kredio loan?
-
What happens if I miss a Kredio payment?
-
How old do I need to be to borrow from Kredio?
-
Can I repay a Kredio loan early?